
Quick answer
UPI (Unified Payments Interface) is India’s real-time payment system that lets you send money directly from one bank account to another using a mobile app. You pay using a UPI ID (like name@bank), a QR code or a mobile number, and confirm with a UPI PIN. It was launched in 2016 by the National Payments Corporation of India (NPCI) and works 24×7.
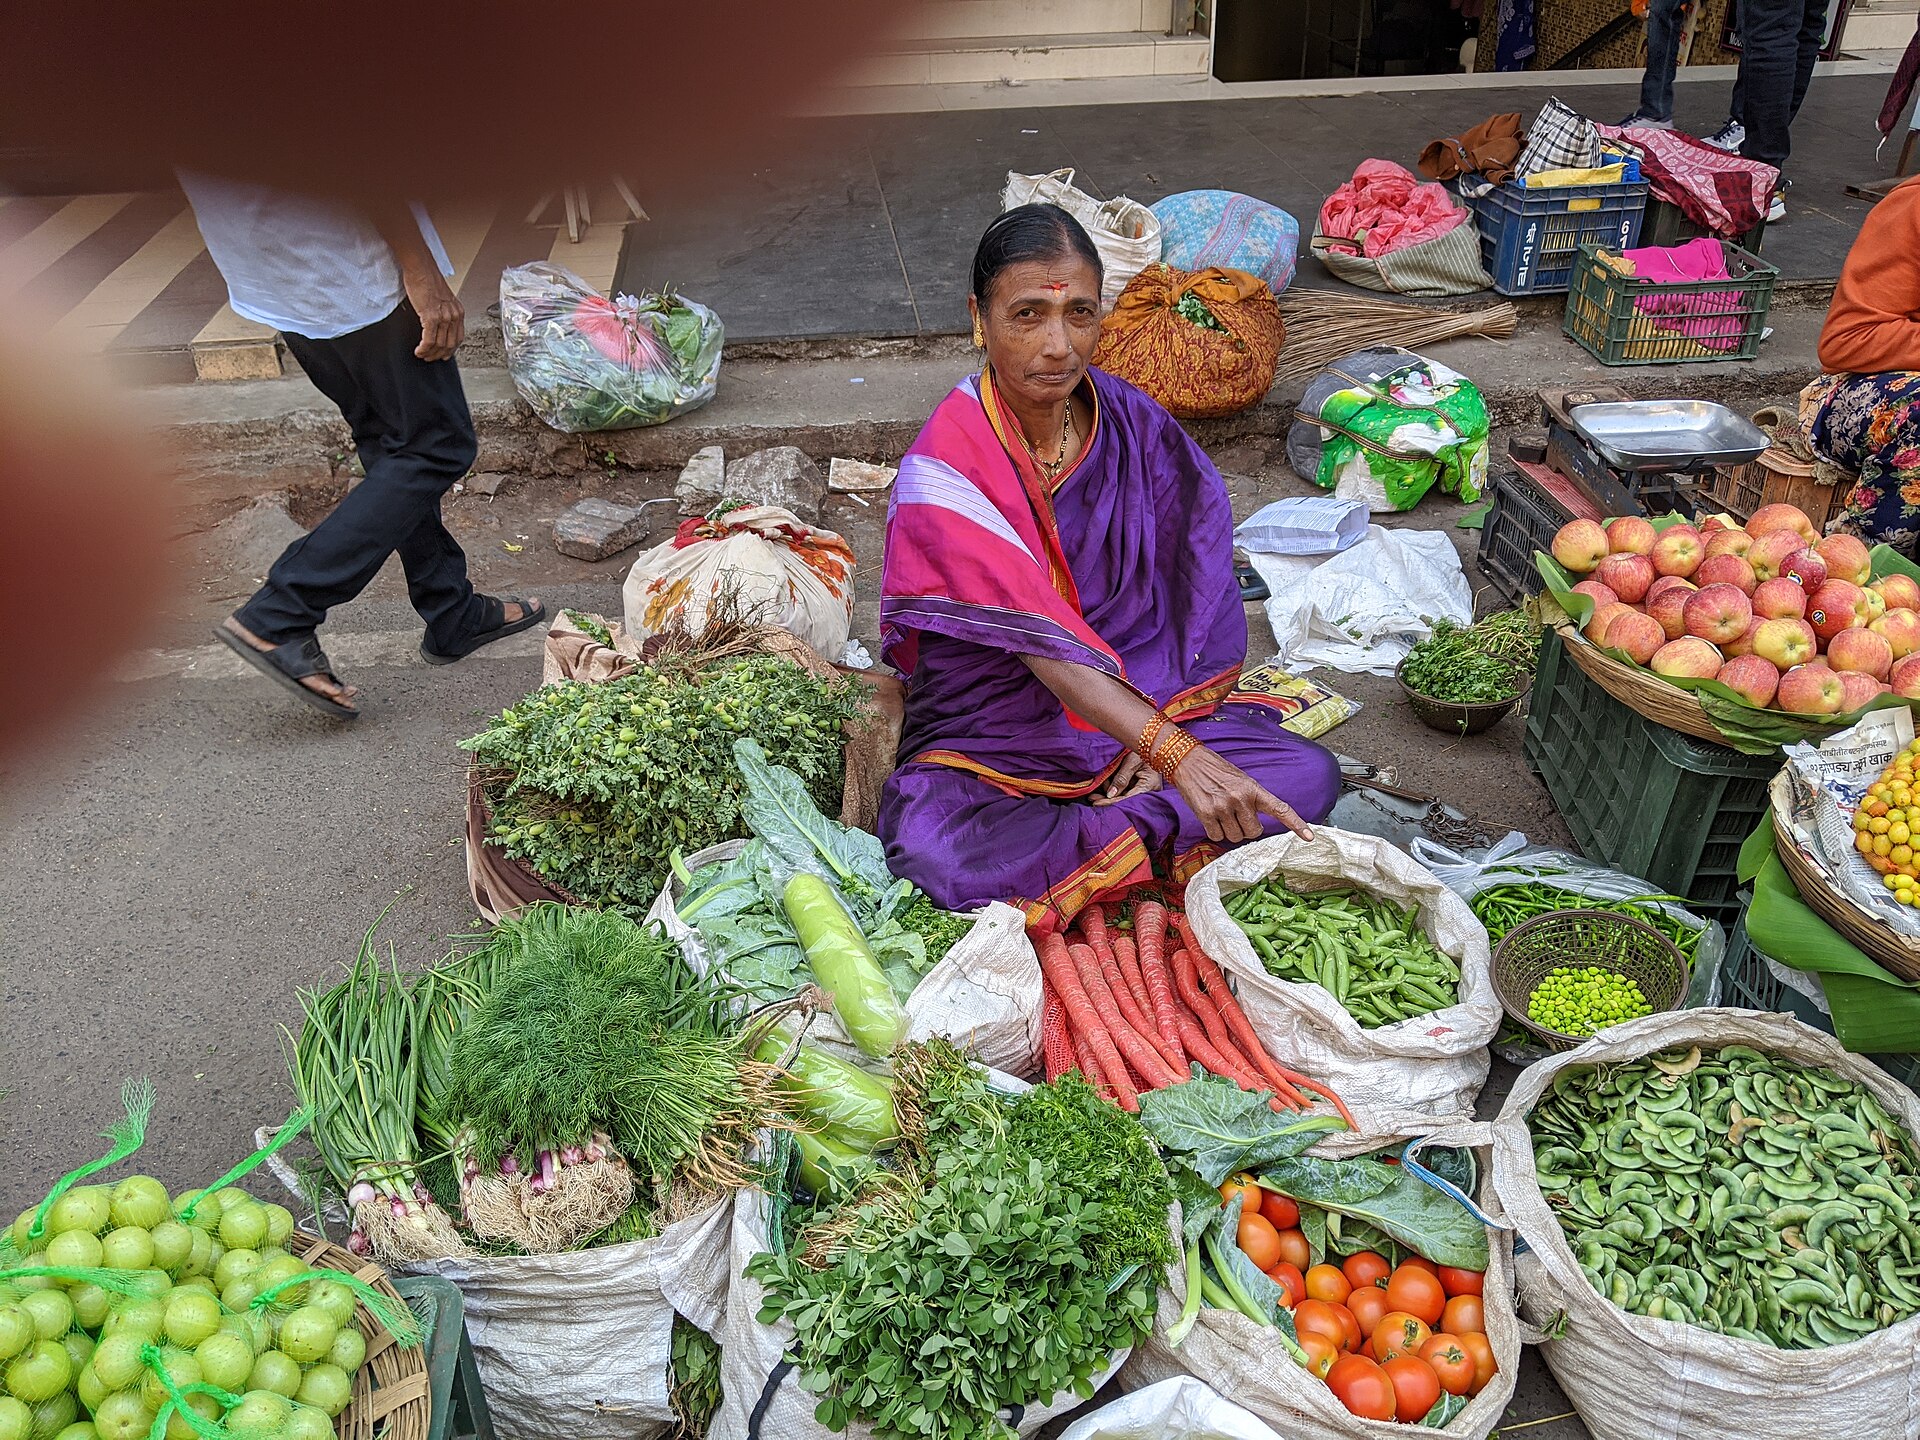
From roadside vegetable sellers to large online stores, UPI has become the most common way to pay digitally in India. It now handles billions of transactions every month.
How UPI works, step by step
- Link your bank account: install a UPI app such as BHIM, PhonePe, Google Pay or Paytm, or your bank’s own app. The app verifies your mobile number registered with the bank.
- Create a UPI ID and PIN: you get a UPI ID and set a secret 4 or 6 digit UPI PIN using your debit card details or Aadhaar-based verification.
- Pay: scan a QR code or enter a UPI ID or number, enter the amount and confirm with your PIN.
- Money moves instantly: NPCI’s system routes the payment between the two banks in seconds, and both sides get a confirmation.
Who runs UPI?
UPI was built by the National Payments Corporation of India, an organisation set up by the Reserve Bank of India and the Indian Banks’ Association to run retail payment systems. Apps like PhonePe or Google Pay are front ends; the money always moves between banks.
Useful UPI features
- UPI Lite: a small on-device wallet for quick, low-value payments without entering your PIN each time.
- UPI AutoPay: set up recurring payments such as subscriptions, SIPs and bills.
- RuPay credit cards on UPI: link a RuPay credit card and pay merchants through UPI.
- UPI 123PAY: UPI for feature phones, through IVR calls and missed calls.
- International UPI: UPI payments are accepted in a growing list of countries, and some banks allow payments abroad.
Is there a limit on UPI payments?
Yes. Most banks cap regular UPI transfers at ₹1 lakh per transaction, with higher limits for specific categories such as tax payments, hospitals and education. Banks can also set their own daily limits and a lower limit for new users in the first 24 hours. Check your bank’s current limits in its app.
Is UPI free?
For individuals, sending and receiving money through UPI from a bank account is free. Some charges apply only in specific merchant cases, such as certain wallet-based payments, and these are borne by merchants.
How to stay safe on UPI
- You never need your PIN to receive money. If someone asks you to enter your PIN to “receive” a payment, it is a scam.
- Check the name shown before you confirm any payment.
- Decline unknown collect requests.
- Never share your PIN or OTP, or install screen-sharing apps at a stranger’s request.
- Report fraud immediately to your bank and on the National Cyber Crime Helpline, 1930, or at cybercrime.gov.in.
Frequently asked questions
What is a UPI ID?
A UPI ID is a unique address, such as name@bank, that is linked to your bank account and lets people send you money without your account number.
Do I need a PIN to receive money on UPI?
No. You only enter your UPI PIN to send money. Anyone asking you to enter your PIN to receive money is attempting fraud.
Who owns UPI?
UPI is run by the National Payments Corporation of India (NPCI), set up by the Reserve Bank of India and the Indian Banks’ Association.
Sources and further reading
Featured image: Photo: Jonathansammy / Wikimedia Commons (CC BY-SA 4.0)